Key Takeaways
- Careful coordination and communication are essential for successful back-to-back closings.
- Preparing documentation and monitoring financing early can prevent costly delays.
Some U.S. home sales involve back-to-back closings—here’s how to navigate them with less stress and fewer surprises. Understanding each step, staying organized, and communicating with everyone involved are crucial to keeping your transition on track.
What Are Back-to-Back Closings?
Back-to-back closing explained
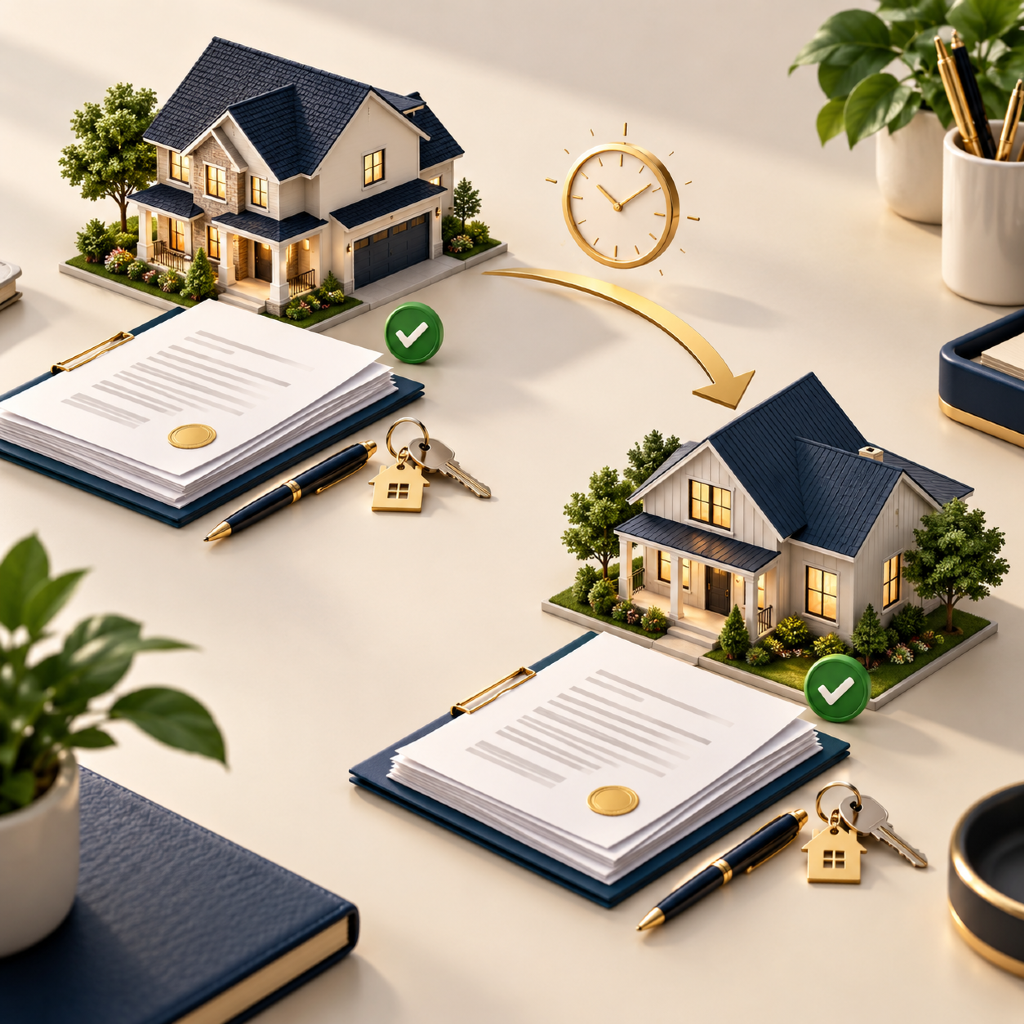
A back-to-back closing happens when you sell your current home and buy a new one on the same day, or within a few days of each other. This arrangement is common for homeowners who want to move directly from one property to another without temporary housing or storage.
Typical reasons for scheduling both sales
Many people choose back-to-back closings to avoid paying two mortgages, reduce the need for short-term housing, and streamline moving. This approach often fits buyers who need to use the equity from their current sale for the new purchase. It also minimizes disruptions for families or individuals with work or school commitments.
Why Do Back-to-Back Closings Matter?
Financial and timing considerations
Back-to-back closings let you avoid carrying the costs of two properties at once. However, they require precise timing—proceeds from your sale may need to fund your purchase. Delays can affect contract obligations, moving plans, and even temporary housing needs.
Impact on buyers and sellers
Timing affects both buyers and sellers. For sellers, a delayed purchase can create stress or added expenses if their sale closes first. For buyers, delays in selling their prior home can jeopardize their ability to secure the next property. In both cases, coordination protects your financial stability and helps ensure a seamless transition.
Step 1: Understand the Timeline
Coordinating sale and purchase dates
Start by mapping out when each closing is scheduled. Your sale should ideally close a few hours before, or at least on the same day as, your purchase. This sequence lets you use the proceeds from your home sale for your next transaction and prevents cash-flow gaps.
Common timeline challenges
Delays can arise from appraisal issues, inspections, loan funding, or documentation. Overlapping commitments between parties, especially around end-of-month periods, can create bottlenecks. Having back-up plans and open communication with all parties can help address these challenges proactively.
Step 2: Prepare Required Documents Early
Essential paperwork for both closings
You’ll need various documents for both the sale of your current home and the purchase of your new property. Common items include your photo ID, the purchase and sale agreement, closing disclosures, proof of insurance, loan documents, and title and escrow statements. Having these ready ahead of time streamlines both closings.
How document delays can impact closing
Missing, inaccurate, or last-minute paperwork can stall closings or require rescheduling. In dual closings, a holdup with one transaction may cascade into delays with the other, since funds or approvals are often interconnected. Double-check requirements well in advance with everyone involved to minimize risks.
Step 3: Monitor Financing Approvals
Mortgage process in dual closings
Coordinating mortgages is one of the trickiest parts of back-to-back closings. If the sale of your current home funds your next purchase, let your lender know upfront that you’re relying on sale proceeds. For buyers, clear communication with both the buyer’s and seller’s lenders helps align fund disbursement and closing dates.
Handling simultaneous buyer and seller approvals
You may need to navigate approval processes as both a buyer and a seller. This means obtaining mortgage payoff statements, coordinating final loan funding, and ensuring buyer financing stays on track. Close monitoring and regular check-ins with both parties will reduce the risk of surprises.
Step 4: Coordinate With All Parties
Involving lenders, escrow, and title companies
Successful back-to-back closings depend on the close cooperation of lenders, escrow agents, title companies, and sometimes attorneys. Each party reviews documents, clears title, oversees the exchange of funds, and ensures all legal requirements are met.
Effective communication strategies
Keep a centralized schedule and checklist to share major milestones and deadlines. Group emails, conference calls, or shared online calendars can help keep everyone in sync. If you don’t understand a process or document, don’t hesitate to ask questions—transparency and clarity reduce risk.
What Can Cause Closing Delays?
Common issues in back-to-back scenarios
Typical causes include buyer financing issues, unresolved inspection items, title issues, inaccurate paperwork, and wire transfer delays. Miscommunication between parties is another frequent obstacle. Unanticipated repairs, last-minute negotiations, or missed deadlines can easily throw off tight timelines.
Ways to prevent last-minute problems
Preparation is essential. Double-check documentation and financing status for all involved parties well before closing day. Request frequent status updates from escrow, title, and both lenders. If possible, schedule both closings earlier in the day or week to allow time for last-minute checks or corrections.
Step 5: Plan Your Move Carefully
Logistics of moving between closings
Moving out and into a new property on the same day requires detailed planning. Schedule movers with buffer time in case closing runs late. Consider temporary storage or overnight accommodations if there’s even a small risk of timing misalignments.
Contingency planning for unexpected delays
Have a backup plan for yourself, your family, and your belongings. Identify short-term options for pet care, child care, and storage in advance, rather than scrambling if a closing is postponed. Communicate your plans to everyone involved so they can adjust if needed.
What You’ll Need for Success
Checklist of essentials
Prepare a written checklist, including:
- Contact numbers for lenders, escrow/title companies, and movers
- Required IDs and legal documents
- Closing disclosures and contracts
- Proof of insurance
- Payment or wire transfer instructions
- Utility setup information for your new home
Who to keep in the loop
Keep all parties—including your spouse or co-borrowers, lenders, title/escrow officers, and movers—informed of updated timelines and any issues that arise. If you’re working with friends or family for support, make sure they’re ready for last-minute requests or schedule changes.
Tips for a Smoother Experience
Proactive planning ideas
- Start the paperwork process as soon as agreements are signed
- Build a one- to two-day buffer between closings if possible
- Keep a running list of tasks and assigned responsibilities
- Verify funds transfer times with your bank, especially for large amounts
Resources for additional support
Online checklists, moving guides, and consumer advocacy groups offer useful tools. Title and escrow professionals can often answer questions about timelines and requirements. Government housing websites and nonprofit housing organizations also offer educational resources to help guide you through the process.